Medicare Advantage Plans Now Fill the Hearing Aid Coverage Gap Left by Original Medicare
- Health
- By Kirsten H. on
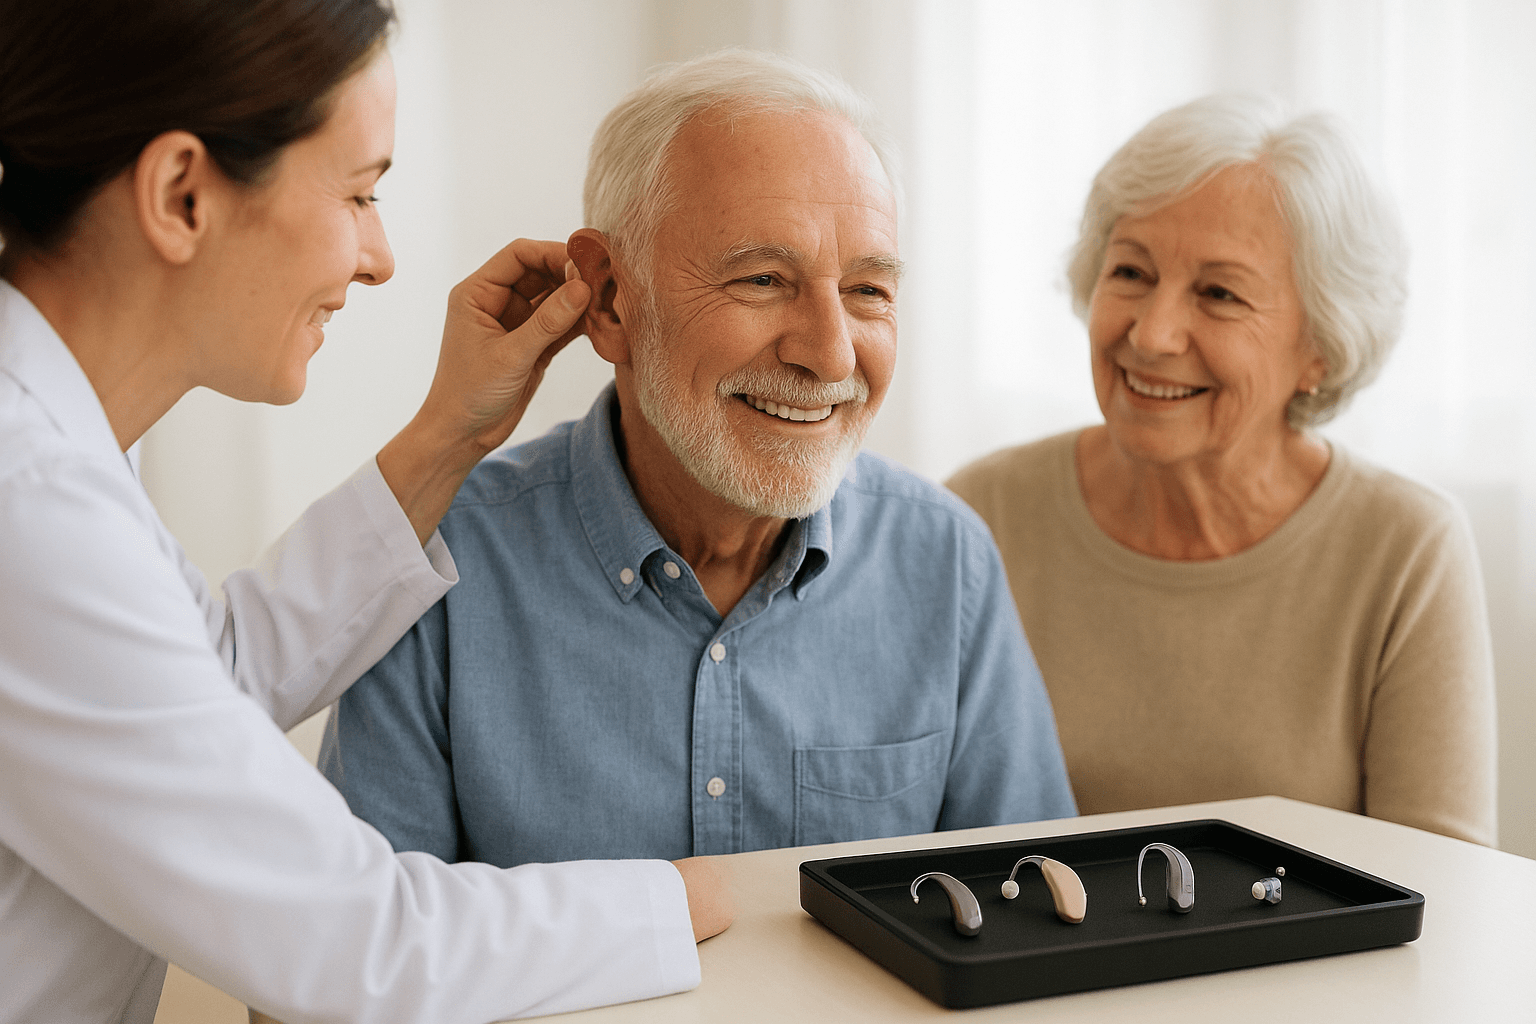
Many older adults live with hearing loss, but Original Medicare has long excluded hearing aids from coverage altogether. Medicare Advantage plans have increasingly taken on that role. For anyone comparing plans during an enrollment period, knowing exactly what is offered can make a meaningful difference in cost.
The Hearing Care Hole in Original Medicare
Original Medicare (Parts A and B) pays for a wide range of hospital and medical services, but hearing care is a clear omission. It covers neither hearing aids nor the exams needed to get fitted for them. Beneficiaries who rely on Original Medicare alone pay the entire cost themselves.
The omission matters because hearing loss is so common. About one-third of people aged 65 to 74 have some degree of it, and the figure rises to roughly half of those older than 75. Since hearing aids often cost thousands of dollars per device, lack of coverage can be a steep financial barrier for people with Original Medicare only.
Where Medicare Advantage Comes In
Medicare Advantage, or Part C, is a privately run alternative to Original Medicare. The law requires it to cover everything Original Medicare covers, and insurers often add supplemental benefits that Original Medicare does not provide. Vision, dental, and hearing coverage are the main examples.
In 2026, nearly every Medicare Advantage plan includes some kind of hearing exam and hearing aid benefit. That is a large reason Part C appeals to people worried about their hearing. Access held steady from 2025 into 2026, and dental, vision, and hearing benefits now work as near-standard features instead of rare extras.
Covered Devices and Brands
The specific brands and models covered vary by insurer and plan. Most plans work with established hearing care networks that stock everything from basic behind-the-ear devices to more advanced receiver-in-canal and completely-in-canal styles. Premium features such as Bluetooth connectivity, rechargeable batteries, and built-in noise reduction appear in benefit packages more often than before.
Manufacturers commonly available include Phonak, Oticon, Widex, Starkey, ReSound, and Signia. Many plans set up the benefit as a fixed dollar allowance, per ear or per pair, that members can apply to the device they choose. About one-third of plans cap reimbursement at a fixed dollar amount, and those caps differ noticeably from plan to plan.
Some insurers go further by partnering directly with hearing benefit programs that handle the whole process, from the first exam to the final fitting. That arrangement can simplify things considerably and sometimes widens the selection of devices.
Costs That Remain
Hearing coverage through Medicare Advantage does not erase costs, so a plan's specific cost structure deserves a look before enrolling. In 2026, the average out-of-pocket maximum for in-network services across Medicare Advantage plans is about $5,421.
Premiums are often low. Many plans charge nothing beyond the standard Part B premium, and about three-quarters of individual Medicare Advantage enrollees with prescription drug coverage pay no additional monthly premium in 2026.
It pays to confirm in advance whether a preferred audiologist or hearing specialist is in-network, because staying in-network generally keeps costs lower. Actual out-of-pocket totals also depend on factors such as any secondary insurance a person has and whether the provider accepts Medicare assignment.
A Lower-Cost Option: Over-the-Counter Hearing Aids
One major change in access came from a federal rule rather than an insurance policy. The FDA finalized a rule in August 2022 allowing adults with mild to moderate hearing loss to buy hearing aids directly over the counter, with no prescription and no professional fitting. The rule took effect that October. These devices generally cost between $200 and $1,000, making them a far cheaper starting point than prescription-grade models.
They do not replace the personalized fitting and professional evaluation included in a Medicare Advantage hearing benefit. Still, people with mild to moderate loss who are not ready to commit to full plan-based coverage can use them as an inexpensive way to begin. For more significant hearing loss, going through a Medicare Advantage benefit to obtain prescription-grade devices remains the more complete route.
Comparing Plans Before You Enroll
Hearing benefits are not the same across all Medicare Advantage plans, so comparing options during an enrollment period is worthwhile for anyone who treats hearing coverage as a priority. Annual enrollment windows let beneficiaries switch plans if their current one no longer suits them.
When comparing, focus on these points:
- The size of the hearing aid allowance
- Which brands and devices are actually covered
- Whether a network audiologist is reasonably close by
- Whether hearing exams are fully covered or only partly
Plan details tend to change from year to year, so checking current terms before re-enrolling helps keep coverage matched to a person's needs.
Key Takeaways
Medicare's handling of hearing health has shifted considerably. Original Medicare still excludes hearing aids entirely, but Medicare Advantage plans have largely made hearing benefits a standard supplemental feature. For the millions of older adults with hearing loss, understanding coverage options, comparing allowances across plans, and staying with in-network providers can substantially change what is affordable. Reviewing available Medicare Advantage plans during an enrollment period is one of the more concrete steps toward better, more affordable hearing care.